Beneath the speculation that dominates cryptocurrency headlines, stablecoins have been quietly winning a practical job: moving money across borders. Pegged to currencies such as the dollar, these tokens let a worker in one country send value to family in another in minutes, at a fraction of the fees charged by traditional remittance corridors, where costs still average several percent of the amount sent and settlement can take days.
Cheaper Corridors, Faster Settlement
The advantage is structural. Conventional remittances hop between banks and agents, each taking a cut and adding delay, and each requiring pre-funded accounts in the destination currency. A stablecoin transfer moves on a single network and converts at the edges, so the expensive middle largely disappears. In corridors plagued by inflation or capital controls, recipients also gain the option of holding a dollar-linked asset rather than converting immediately into a weakening local currency — a feature users value at least as much as the fee saving.
Regulators, after years of hostility, are increasingly setting terms rather than bans. New stablecoin laws in major markets require issuers to hold reserves in cash and short-term government debt, publish attestations and redeem at par on demand. That framework deliberately favours large, boring issuers over experimental designs — an explicit reaction to the collapse of algorithmic stablecoins that promised the same stability with none of the reserves and delivered neither. Further background is available in our crypto coverage for readers following this story.
Regulators Set the Terms
Traditional finance is responding by joining rather than fighting. Payment networks and banks have launched stablecoin settlement services, and remittance giants now route part of their volume over token rails behind the scenes, keeping their familiar storefronts while cutting their own costs. The likely end-state, analysts argue, is invisibility: customers will send money as they always have, unaware that the plumbing underneath changed, which is usually how financial infrastructure revolutions actually conclude.
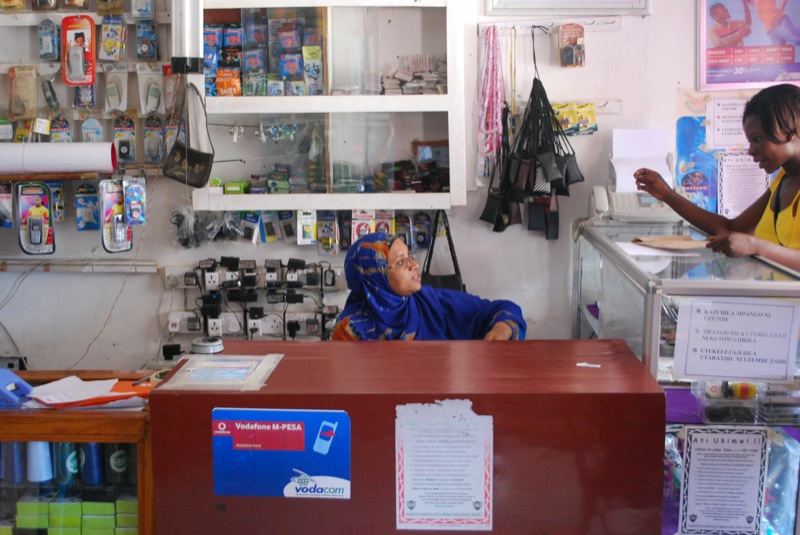
The risks deserve their due. An issuer failure, a frozen reserve account or a smart-contract exploit can strand funds faster than any bank run, and consumer protections in most markets still lag those covering bank deposits. Recipients in cash-based economies depend on local agents to convert tokens to spendable money, reintroducing cost and counterparty risk at the last mile. Illicit finance concerns, meanwhile, keep compliance teams and regulators in permanent negotiation with the industry. Additional reporting from Reuters Technology provides further detail on the background.
Risks That Remain
Even with those caveats, the trajectory is clear. Remittances are one of the largest financial flows on earth, sent by people who can least afford to lose six percent of them to friction. A technology that cuts that cost to under one percent, and settles before dinner rather than next week, does not need hype to justify itself. It needs reserves, rules and reliability — the unglamorous work now under way. The debate is expected to continue, with further announcements anticipated before the end of the quarter from the main organisations involved.
